The Contract Trap — How the Fee Stays in Switzerland
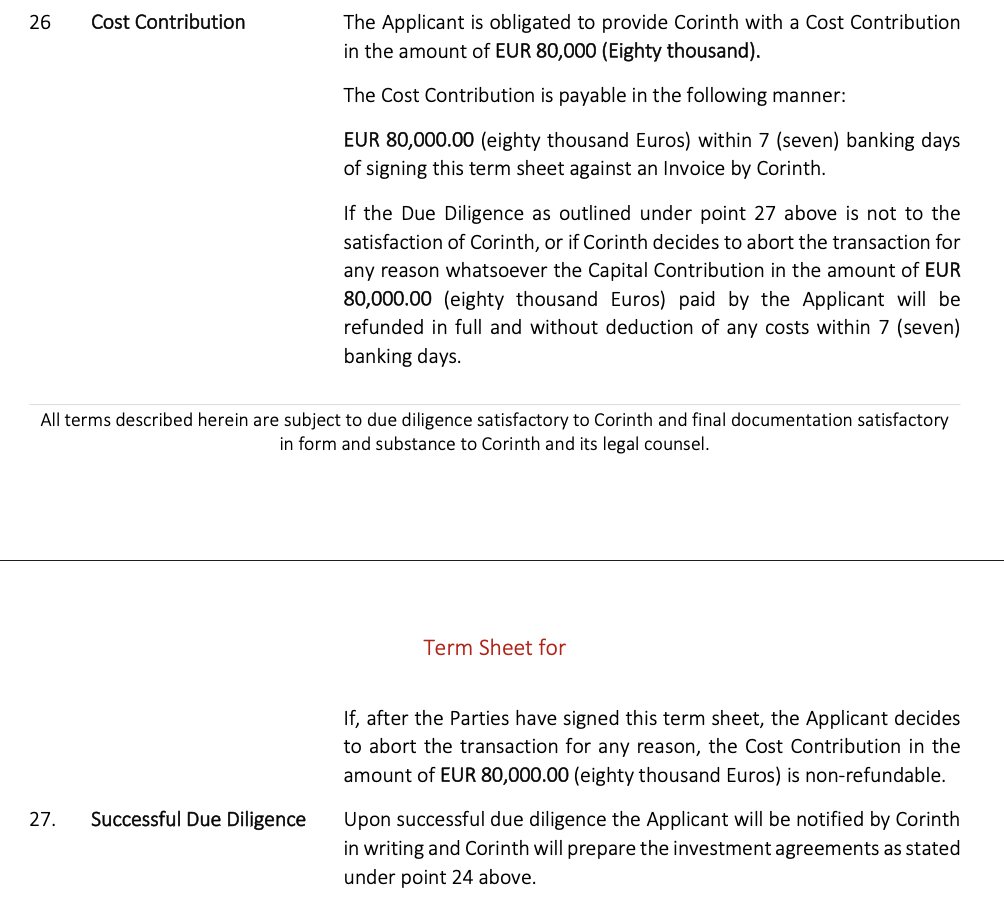
Read together, the documents give Corinth many ways out and the client very few. In practice, the structure works as an exit plan. The fee is paid in Switzerland under Swiss law. The promise to fund is moved to England, under English law, to a UK special-purpose vehicle that in several cases did not exist. When that promise collapses — and the contract allows it to collapse “for whatever reason” — complainants described the Swiss entity as retaining the fee while no entity accepts an obligation to refund it.
The contract suite
| # | Document | Law / forum | Counterparty | Key content |
|---|---|---|---|---|
| 1 | Term Sheet | Swiss law; Court of Chur exclusive | Corinth Group of Switzerland (Stadtgartenweg 6, Chur) | Art. 6 & 30 'regulated and licensed' funding; Art. 26 EUR 80,000 Cost Contribution + 7-day refund |
| 2 | Debenture Facility Agreement | English law | UK SPV ('Lender') | Funding obligation; Clauses 5.6, 6.1, 6.6 |
| 3 | Promoter Security Agreement | English law | UK SPV | Security from promoter |
| 4 | Borrower Security Agreement | English law | UK SPV | Security from borrower |
| 5 | Share Purchase Agreement | English law | UK SPV | Equity element |
What Corinth charges
| Facility / situation | Amount |
|---|---|
| Historical / general advance fee | €30,000–€80,000 |
| Article 26 Cost Contribution | €80,000 |
| LDF 1 | €350,000 — €50k + €300k |
| LDF 2 | €5,000,000 |
| Certain complainant total losses | €400k+ |
How the trap works — six steps
The Claim: “Regulated and Licensed Investment Funds”
Term sheet states funding from “regulated and licensed entities” (Article 6) and “regulated and licensed Investment Funds” (Article 30). Both contradicted by the regulatory record. CySEC AIFM licence revoked after 7.5 months. The first fund was dissolved in January 2023; its successor is in members' voluntary winding-up. No FINMA authorisation. Swiss AGs are unregulated private companies.
The Fee: EUR 80,000 Collected Under Swiss Law
Client signs term sheet with Corinth Group of Switzerland (Stadtgartenweg 6, Chur). Pays EUR 80,000 “Cost Contribution” to Corinth Management Services AG (CHE-103.982.016). Article 26: fees “will be refunded in full and without deduction of any costs within 7 banking days” if Corinth aborts. Swiss law. Court of Chur exclusive jurisdiction.
The Switch: Counterparty Becomes a Phantom UK SPV
After payment, 5 execution contracts replace Corinth Switzerland with a UK SPV at Pluto House, 6 Vale Avenue, Tunbridge Wells, TN1 1DJ (serviced office). Debenture, Promoter Security and Borrower Security agreements name “SPV” as lending party. In multiple known cases, the named SPV was never actually incorporated — binding agreements with a non-existent entity. English law.
The Escape: Three Built-In Exit Clauses
Clause 5.6 — “due to whatever reason… this Agreement will become null and void.” Clause 6.1 — “for reasons beyond the Lender's control,” commitment cancelled. Clause 6.6 — if Corinth “discovers any material changes” (self-assessed), it can cancel AND claim damages from the client. EUR 80K paid under the term sheet (Swiss law). Funding obligation in the debenture (English law). When the debenture goes “null and void,” complainants describe the Swiss entity as retaining the fee while no entity accepts an obligation to refund it.
The Script: Identical Excuses to Different Clients
Identical scripted excuse: “Trump's reciprocal tariffs with Switzerland are hurting profitability. Bank of America has pulled out as our key funder.” Tariffs on goods have no obvious bearing on a financing business, and the same explanation was given to different clients months apart. No public evidence of any Bank of America–Corinth relationship. BofA Swiss operations serve Fortune 500s with minimum PE ticket ~USD 150M.
The Result
No known complainant has been funded. None has been refunded. Swiss entity retains all fees. UK SPV dissolved. Recovery requires litigating in Chur under Swiss law.
Why enforcement is so hard
Sue in Switzerland and you face a foreign court, foreign lawyers and costs that can exceed the €80,000 you lost. Sue in England and the “Lender” is a shell with no assets — or was never incorporated. Complainants describe difficulty identifying an entity from which they can enforce a refund. Complainants describe the structure as designed so that no single authority can easily act.
Warning signs for prospective clients
- No current regulatory authorisation — the only licence was revoked in 7.5 months.
- Contracts withheld until after payment — 'trust and respect the relationship.'
- Refund clause never honoured — in every documented case.
- Counterparty switch — Swiss fee, UK 'Lender', sometimes never incorporated.
- Three escape clauses — 'whatever reason', 'beyond control', 'material changes'.
- Compulsory liquidation — Corinth Management Services Ltd, January 2026.
- Unverified jurisdictions — Spain, Mauritius, Ireland, Singapore: nothing on any register.
- Zero verified completed deals — Morepen denied; Addvalue unproven.
The same facility names appear in broker advertising that promises “no upfront fees”. See broker marketing.
If you are approached
(1) Verify all claims against official registers before paying anything; (2) search the entity and individual names on Ripoff Report and consumer platforms; (3) request independently audited financial statements; (4) take independent legal advice before signing or paying. Already paid? Contact your bank, your regulator and law enforcement.